NylaBank Secures $550K Pre-Seed to Build Pan-African Islamic Banking Platform
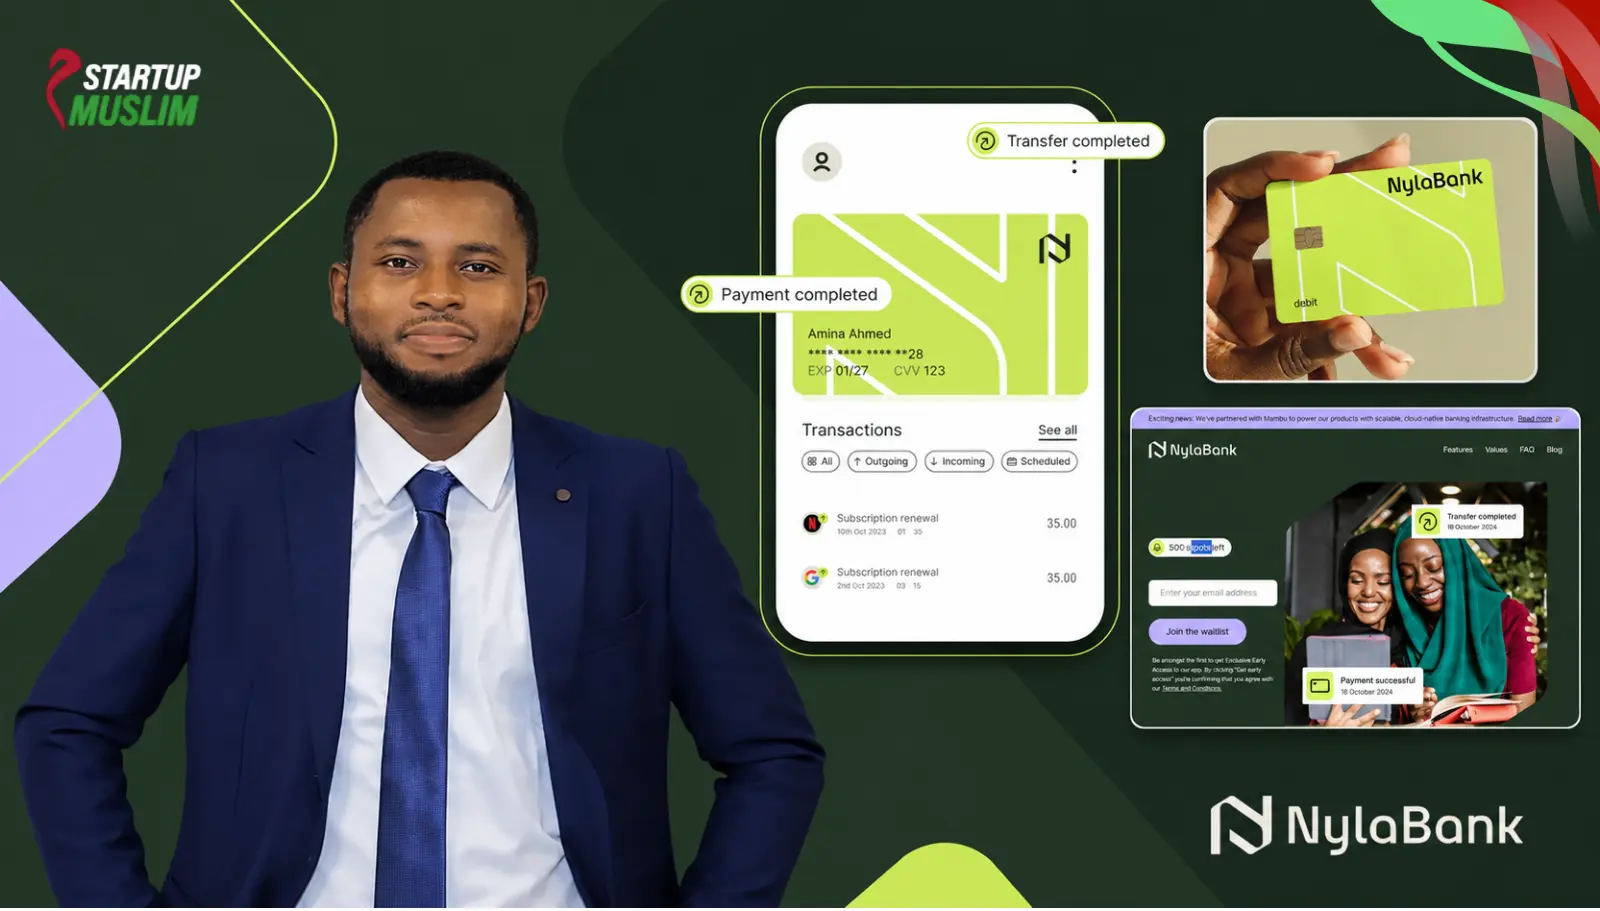
NylaBank has secured an oversubscribed $550,000 pre-seed round to build a pan-African Islamic banking platform. Led by Ingressive Capital with participation from a Mubadala Capital partner, the funding will fuel the company’s launch in Ghana before a planned expansion into Nigeria and the broader continent.
Founder Mubarak Sumaila built NylaBank to solve a specific, high-friction problem: millions of consumers possess access to traditional banks but refuse to use them due to religious and ethical conflicts. With an estimated 450 million Muslims across Africa, the startup targets a massive demographic historically underserved by conventional financial institutions.
Deploying Asset-Light Infrastructure
Rather than burning capital on acquiring banking licenses in every target market, NylaBank leverages an asset-light strategy. The startup partners with licensed local banks to hold deposits while managing the technology stack and customer experience.
To power this infrastructure, NylaBank deployed Mambu’s core banking system, which features dedicated Islamic finance capabilities. This technological foundation allows the company to scale operations quickly across borders without rebuilding its backend for each new regulatory environment.
The goal is not to create a niche banking app. It is to help build financial infrastructure for an underserved population at continental scale.
Revenue Model and Product Roadmap
The company enters a market that requires deep trust and high utility. To transition its 35,000-person waitlist into active users, NylaBank plans to sequence its product rollouts. The initial launch targets retail customers, with subsequent phases introducing business banking.
NylaBank relies on several core drivers for user acquisition and retention:
- Payments and Remittances: Facilitating high-frequency domestic transactions and capturing cross-border capital flows from the GCC, Europe, and North America.
- Shariah-Compliant Financing: Offering alternatives to interest-based lending, including ethical buy-now-pay-later (BNPL) structures.
- Wealth Management: Introducing Sukuk, Shariah-compliant stocks, and exchange-traded funds (ETFs) for retail investors.
The revenue model directly aligns with this product suite. NylaBank will generate capital through transaction fees, foreign-exchange spreads, remittance charges, and profit-sharing margins on financing and investment products. As users expand their financial activities, the platform scales its revenue per customer.
From Founder Burnout to Global Ambition
The thesis behind NylaBank originated far from a venture capital boardroom. Following a successful exit from his previous startup and a period of burnout, Sumaila spoke with his mother about money management. She explained that traditional banking products compromised her community's values—specifically concerning interest, speculation, and unethical investments.
Sumaila recognized that financial exclusion was not purely an infrastructure issue; it was a values mismatch. By structuring a platform around transparency, fairness, and equity, NylaBank aims to bridge this gap.
While the immediate focus remains on executing the Ghana launch and penetrating the West African market, the long-term objective is vast. Sumaila intends to utilize deep market penetration, strategic acquisitions, and robust partnerships to eventually build the largest Islamic bank in the world.